Author Archives: support

Robinhood Users Favour Simplicity in Stock Selection

Millions of investors using Robinhood tend to favour stocks that are simpler and easier to understand, according to new research from Washington State University (WSU). The study also found that these less complex stocks outperformed more complicated firms during the period examined, suggesting that a preference for simplicity may have benefited investors.

The research examined investment patterns among users of Robinhood, a popular commission-free mobile app and web-based trading platform. According to the company, Robinhood has about 28 million users, with an average age of 35. Researchers say understanding the investment behaviour of these younger, digitally savvy investors is increasingly important as they play a larger role in financial markets.

“These preferences have market effects,” said Mario Reyes, professor and chair of the Department of Finance & Management Science in WSU’s Carson College of Business. Reyes noted that greater demand from Robinhood users for simpler stocks could influence the market. The findings also have implications for investor relations, suggesting companies should communicate effectively with inexperienced individual investors as well as large institutional investors.

The study, published in Finance Research Letters, was co-authored by Ruixue Gao, who completed her PhD at WSU and has since joined Central Connecticut State University, George Jiang, professor and Investment Management Chair in Finance & Management Science, and Reyes. Founded in 2013, Robinhood Markets allows users to trade stocks, options and cryptocurrencies while also offering other financial services.

“The platform is very, very popular, and generally, these investors are very young,” Gao said. “We want to know what young people care about because they are the future of the stock market.” Previous research has found that Robinhood investors are often attracted to stocks with high “idiosyncratic volatility,” meaning their price movements may differ substantially from those of the broader market.

To examine whether simplicity also influenced investment decisions, the researchers analysed Robinhood holdings from May 2018 through August 2020. They assessed companies using two measures of complexity. Accounting complexity was measured by the number of accounting items reported in a company’s annual U.S. Securities and Exchange Commission filings. In contrast, organisational complexity was based on the number of businesses or operating segments within a firm.

The analysis showed that more Robinhood users invested in companies that were less complex and easier to analyse. Importantly, the relationship remained even after researchers controlled for company size, indicating that investors’ preference for simplicity was not merely a tendency to favour smaller firms. The simpler stocks preferred by Robinhood investors also outperformed more complex stocks during the study period.

Across different measures and comparisons, the preference for simplicity remained consistent. “What stands out is that Robinhood investors consistently gravitate toward companies that are easier to understand,” Reyes said. “Whether we measured complexity through financial reporting or business structure, the pattern was the same.” The findings highlight how a growing generation of individual investors may influence markets through a preference for companies whose finances and business models are relatively straightforward.

More information: Ruixue Gao et al, Robinhood: Simple app simple stocks, Finance Research Letters. DOI: 10.1016/j.frl.2026.110446

Journal information: Finance Research Letters Provided by Washington State University
Rideshare Expansion Boosts Local Economies and Flexible Job Opportunities, Study Finds

Ride-hailing has become a routine part of urban life in the United States, offering convenient transportation for passengers and flexible work for drivers. Yet the broader economic effects of services such as Uber and Lyft have been difficult to measure. As the platforms expanded across hundreds of cities over the past decade, questions remained about whether their growth translated into measurable benefits for local economies and labour markets.

A new study from Carnegie Mellon University and Oxford Saïd Business School examined the launch of ridesharing services across 167 U.S. metropolitan areas between 2010 and 2019. Because these transportation network companies (TNCs) entered different cities at different times, researchers were able to compare economic trends before and after their arrival while accounting for regional differences. The team combined publicly available workforce and economic data with statistical methods designed to evaluate policies and services introduced gradually over time.

The researchers found two notable changes after Uber and Lyft entered a region: GDP per capita increased, and the number of seasonal, temporary or intermittent jobs rose. They found no statistically significant effects on overall employment or wages. Together, the findings suggest that ride-hailing services may have expanded access to flexible employment while generating additional economic activity associated with greater mobility.

“Uber and Lyft have made a lot of claims over the years about boosting citywide economies and providing flexible jobs,” said Jeremy Michalek, professor of engineering and public policy and mechanical engineering at Carnegie Mellon University. “We find that the data do, in fact, corroborate some of these claims with evidence that Uber and Lyft have increased intermittent employment and economic output in US cities as they entered.”

Published in Nature Cities, the findings also offer insights into the broader effects of the gig economy. An increase in intermittent employment without a corresponding rise in total employment suggests that digital platforms can reshape labour markets by changing how and when people work rather than simply creating more jobs overall. Higher GDP per capita may also reflect wider economic ripple effects, as easier transportation allows passengers to make trips they otherwise might not take, helps workers travel to jobs and creates new patterns of local spending and economic activity.

The researchers also examined whether Uber and Lyft launched in cities that were already experiencing economic growth. They found no meaningful pre-existing trends in employment or wage growth, strengthening the evidence that the changes were associated with the arrival of ride-hailing services. Michalek noted that ride-hailing has produced a wide range of effects, from disrupting the taxi industry and increasing congestion to reducing discrimination and intoxicated driving. “This new evidence suggests they have had measurable positive effects on local economies, too.” The study provides policymakers and researchers with new evidence for understanding the broader economic footprint of ride-hailing and the growing gig economy.

More information: Adam Koling et al, Effects of Uber and Lyft on jobs, wages and GDP, Nature Cities. DOI: 10.1038/s44284-026-00478-0

Journal information: Nature Cities Provided by College of Engineering, Carnegie Mellon University

When Sugar Cravings Win Over Health

Researchers at HSE University–Perm used electroencephalography (EEG) to examine how sugar cravings and health consciousness influence consumers’ evaluations of Cola-flavoured beverages. Their findings suggest that people who place greater importance on healthy eating experience more cognitive effort when deciding how much they are willing to pay for a drink and ultimately choose to spend less. The study was published in the British Food Journal.

Consumers often face a trade-off between enjoying the taste of indulgent foods and considering their health value. This dilemma is particularly relevant for sugary drinks, which are typically chosen for pleasure rather than nutrition. The researchers investigated how this internal conflict affects consumers’ willingness to pay, defined as the maximum amount they would spend on a product.

The study involved 40 adults aged 18 to 59. Participants first completed questionnaires measuring their cravings for sweets and their attitudes toward healthy eating. They then tasted six Cola-flavoured beverages and rated each drink’s taste while indicating the highest price they would be willing to pay for a 330-millilitre can. No actual purchases were made.

The tasting consisted of two stages. In the first, participants sampled the beverages unthinkingly from identical clear glasses without knowing the brand. In the second, the packaging was revealed, allowing participants to see the brand name and sugar content. Throughout both stages, researchers monitored brain activity using EEG to understand the decision-making process better.

People with stronger cravings for sweets were willing to pay more for the beverages during the blind tasting, even though they did not rate the drinks as tasting better than other participants. Once the packaging and product information were revealed, however, these participants gave higher taste ratings and remained willing to pay more. The researchers suggest that familiar branding strengthened expectations of enjoyment, increasing the drinks’ perceived value.

Health-conscious participants showed a different pattern. During the blind tasting, EEG recordings revealed greater beta-wave activity in the prefrontal cortex when they decided how much they were willing to pay, indicating greater cognitive effort. This increased mental processing was associated with lower willingness to pay. Interestingly, the relationship disappeared once the product packaging and nutritional information were visible.

The study also found that demographic factors influenced purchasing decisions. Younger participants and women were generally willing to pay more for the beverages, while people with higher incomes were prepared to spend more during the branded tasting. Education level, regular consumption of Cola-flavoured drinks and the drinks’ sugar content did not significantly affect willingness to pay.

According to study co-author Daria Semyonova, the findings indicate that the conflict between taste and health emerges not while tasting the beverage but when consumers decide how much it is worth. In that decision-making process, cravings for sweets appear to outweigh health concerns, particularly when familiar brands reinforce expectations of pleasure.

More information: Daria Semenova et al, The taste–health dilemma in hedonic food consumption: behavioral attitudes, neural responses and willingness to pay for cola-flavored drinks, British Food Journal. DOI: 10.1108/BFJ-11-2025-1589

Journal information: British Food Journal Provided by National Research University Higher School of Economics

A Better Approach to Federal Stress Testing

Could another financial crisis on the scale of 2008 happen again? And if it did, how well would today’s banks withstand the shock? To answer those questions, government regulators regularly stress-test large financial institutions, assessing how their balance sheets would perform under extreme economic conditions. A recent Federal Reserve Board stress test found that even in a severe recession, the largest U.S. banks could collectively absorb losses of $708 billion while remaining financially sound and able to continue lending.

Most stress tests rely on historical crises or hypothetical scenarios that closely resemble them. However, new research from the McCombs School of Business at The University of Texas at Austin suggests that the most memorable market crashes are not always the best indicators of future financial risk. Instead, the researchers propose a broader, data-driven method for identifying the scenarios most likely to expose weaknesses in financial institutions.

The new approach, developed by Rui Gao, associate professor, and Stathis Tompaidis, professor, in the Department of Information, Risk, and Operations Management, uses multifaceted market data rather than focusing primarily on headline-making events. In experimental tests, their models outperformed an existing regulatory approach by more effectively identifying the scenarios that produced the largest losses. “It’s not necessarily the large market moves, the headline days, that are the best days to use,” Tompaidis says. “It’s days where the stresses are complemented with each other.”

Stress testing has a long history. Tompaidis notes that the concept dates back to the 17th century, when gunsmiths “proof tested” gun barrels by firing them with heavy loads to see whether they would fail. Modern financial regulators use a similar principle, exposing institutions to hypothetical economic shocks to evaluate how their profits, losses, and capital positions would respond under pressure.

Designing those scenarios, however, is challenging. Regulators must balance transparency with effectiveness. Revealing too much about how scenarios are selected could allow financial institutions to tailor their portfolios to perform well on specific tests rather than genuinely improving resilience. Because stress testing is also costly and time-consuming, each scenario should be carefully chosen to reveal the greatest potential vulnerabilities.

Existing stress tests often centre on well-known market crashes, when stock prices, interest rates, currencies, commodities, and market volatility all shifted dramatically. But Gao explains that real-world risks are more complex. Different financial stressors can move in different directions, meaning several famous crises may actually test institutions in similar ways. A better approach is to combine severe yet complementary scenarios that uncover different types of risk.

Working with former McCombs doctoral student Rohit Arora, the researchers evaluated 2,828 historical market scenarios spanning April 2008 to June 2019. Their algorithm selected four scenarios with complementary stress factors and tested them against 1,000 simulated investment portfolios. The researchers’ scenarios identified the single worst historical outcome about 40% of the time, while their most accurate model successfully captured the five worst outcomes approximately 95% of the time. Compared with the Commodity Futures Trading Commission’s baseline scenarios, the new approach consistently detected more severe losses.

The findings suggest that combining multiple, complementary market stressors provides regulators with a more accurate picture of financial risk than relying on famous market crashes alone. The approach could also reduce the number of stress tests needed while improving their effectiveness. Ultimately, the researchers hope their models will help regulators better identify financial vulnerabilities before the next crisis arrives. As Gao puts it, “We want to choose scenarios to help regulators to evaluate risks more accurately.”

More information: Rohit Arora et al, Choosing Scenarios to Estimate Resilience and Stress Test Financial Institutions, Management Science. DOI: 10.1287/mnsc.2024.06126

Journal information: Management Science Provided by University of Texas at Austin

Islamic Bonds Boosted Corporate Capital Access

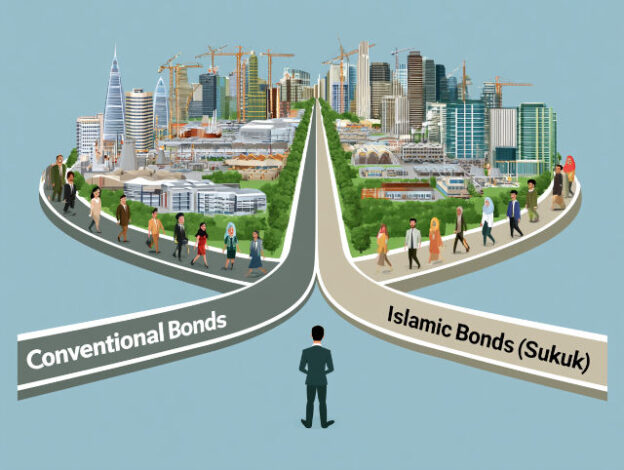
In the late 1990s, Malaysia introduced a new way for corporations to raise capital by allowing the issuance of Shariah-compliant bonds, known as sukuk. Unlike conventional bonds, sukuk are structured to comply with Islamic law, which prohibits the payment or receipt of interest. The approach proved highly successful, according to a comprehensive study co-authored by UC Riverside finance professor Jean Helwege. Published in the Journal of Financial Economics, the research found that Islamic bonds attracted billions of dollars in new investment without displacing the conventional corporate bond market, ultimately expanding businesses’ access to financing and supporting Malaysia’s economic growth.

The researchers analysed two decades of Malaysia’s corporate bond market after sukuk were introduced in 1997. Rather than competing directly with conventional bonds, Islamic bonds attracted investors and institutions that would not otherwise purchase interest-bearing securities. “The overall finding was that these bonds increased in popularity,” Helwege said. “People did like to buy them, but it didn’t make the conventional bonds go away. The result was that there’s more financing overall, and it does seem to have been helpful to the growth of the Malaysian economy.” The findings challenge the assumption that introducing a new financial product divides an existing market, showing instead that sukuk expanded the total pool of capital available to businesses.

Although Islamic bonds produce returns that closely resemble those of conventional bonds, they are structured differently to comply with religious principles. Instead of explicitly paying interest, sukuk use contractual arrangements based on profit sharing or asset-backed financing that generate similar economic outcomes. “From an investor’s perspective they look extremely similar,” Helwege said. “But there are details in the structure that make them consistent with the Islamic world.” Sukuk also cannot finance businesses involved in activities prohibited under Islamic law, such as gambling. While often described as profit-sharing instruments, Helwege noted that they differ from equity because investors still expect to recover their principal without giving up ownership in the company.

Malaysia provided an ideal setting for the study because it deliberately developed an Islamic capital market alongside its conventional bond market. This dual system allowed researchers to observe how companies and investors responded when presented with two securities offering similar financial returns but different religious eligibility. Many corporations chose to issue both conventional bonds and sukuk, enabling them to reach traditional investors as well as Islamic investors, particularly those in wealthy Gulf states and other regions. Even as Islamic bond issuance expanded, conventional bonds continued to play a significant role in corporate financing.

The study also found that pricing differences between conventional bonds and sukuk remained relatively modest. Although issuing Islamic bonds requires additional costs, including obtaining religious certification, companies benefited from access to a broader investor base. In the late 1990s, annual sukuk issuance totalled less than US$2.5 billion, compared with US$5 billion to nearly US$18 billion in conventional bond issuance. By 2017, Islamic bond issuance had climbed to more than US$20 billion annually, while conventional bond issuance remained relatively stable. The growth illustrates how sukuk evolved from a niche financial product into a major source of corporate funding without weakening the conventional bond market.

The findings have implications beyond Islamic finance. As markets increasingly develop specialised investment products tailored to specific groups of investors, including environmentally and socially responsible funds, the research suggests that new financial instruments can increase access to capital when they attract investors who would otherwise remain on the sidelines. For Helwege, the study’s central message is clear: accommodating religious values strengthened rather than fragmented the market. “It was a popular product,” she said. “The conventional bonds didn’t disappear. There was simply more financing available overall.”

More information: Antje Berndt et al, The impact of introducing a (nearly) redundant security: Evidence from Malaysian corporate bonds, Journal of Financial Economics. DOI: 10.1016/j.jfineco.2026.104310

Journal information: Journal of Financial Economics Provided by University of California – Riverside

Why Do Some Businesses Pay Less Tax?

Few issues spark more public debate than large corporations paying little—or sometimes no—federal income tax. Since 2018, the U.S. federal corporate income tax rate has been 21%, its lowest level in decades, down from a peak of 53% in 1969. Yet many companies pay even less because of deductions, credits, and other provisions that reduce their effective tax rate—the share of income they actually pay in tax. According to the Institute on Taxation and Economic Policy, at least 88 profitable corporations paid no federal income tax in 2025. Why do some businesses pay more tax than others, and what explains these differences?

A new study from the McCombs School of Business at The University of Texas at Austin analysed three decades of research on corporate tax avoidance to identify the factors that have the greatest influence on companies’ effective tax rates. The researchers compared 31 commonly cited explanations using more than 8,000 annual observations of publicly traded U.S. companies over two decades. Their findings suggest that low tax rates are driven less by manipulation than by a combination of business decisions, financial circumstances, and tax policy. “There’s all this noise about companies that don’t pay taxes or have very low tax rates, but if you dig in, a lot are driven by pretty benign factors,” says Andrew Belnap, assistant professor of accounting.

The study found that investment choices are the single biggest driver of differences in corporate tax rates, accounting for 34% of the variation in cash taxes paid. Companies investing heavily in research and development often benefit from valuable tax credits. Businesses with substantial intangible assets, such as patents and trademarks, can also lower taxes because these assets are easier to allocate across international borders. In addition, firms that earn income through subsidiaries in lower-tax countries generally face lower overall tax burdens.

Financial pressures also play a major role, explaining 21% of the variation in tax rates. Companies facing cash constraints are more motivated to minimise tax payments because preserving cash is essential to their operations. The researchers also found that many tax differences arise naturally from a company’s operating profile rather than deliberate tax planning. Factors such as profitability, accumulated operating losses, and debt levels all influence the amount of tax a business ultimately pays. Even within a single corporation, different business divisions can face markedly different tax rates because of the nature of their activities.

The study also challenges several common assumptions about corporate tax avoidance. Characteristics that often attract public attention—including CEO compensation, board composition, ownership structure, and company size—were found to explain relatively little of the variation in effective tax rates. One notable exception was the influence of individual executives. The researchers found that managers leave a distinct “tax fingerprint” that often follows them from one company to another, with management-related factors accounting for nearly one-quarter of the variation in corporate tax rates.

The findings offer policymakers a clearer picture of where reforms could have the greatest impact. Rather than relying primarily on increased audits or changes to corporate governance, the researchers suggest focusing on rules governing research and development incentives, intangible assets, and international income reporting. Improving transparency around where companies earn their income could also help strengthen tax policy. As Belnap notes, companies largely respond to the incentives built into the tax system, meaning that reducing tax avoidance ultimately depends on changing those incentives rather than simply increasing enforcement.

More information: Andrew Belnap et al, Explaining Corporate Tax Avoidance, Management Science. DOI: 10.1287/mnsc.2024.04839

Journal information: Management Science Provided by University of Texas at Austin

Researchers Say Women Need Better Support to Thrive in Business

Researchers are calling for a fundamental rethink of how women are supported to start and grow businesses, arguing that existing approaches have not kept pace with the digital transformation of the workplace. A new study from the University of East London suggests that while long-standing barriers—including unequal access to finance, limited professional networks and greater caring responsibilities—continue to affect women entrepreneurs, digital technologies now offer new opportunities to overcome many of these challenges. The researchers argue that policies and business support programmes should place digital innovation at the centre of efforts to help more women succeed in entrepreneurship.

Published in the Journal of Management Development, the study examines 50 years of research encompassing more than 12,000 academic papers before proposing a new framework for women’s entrepreneurship in the digital age. The researchers contend that digital workplace innovation—including remote and hybrid working, cloud-based technologies and online collaboration tools—can create more flexible pathways into entrepreneurship. They argue that developing digital skills can also help women build confidence, expand professional networks, gain business experience and access leadership opportunities that were previously more difficult to attain.

The study also highlights the importance of mentorship in fostering entrepreneurial success. Experienced women entrepreneurs, the researchers say, play a critical role in supporting the next generation by sharing practical knowledge, offering guidance and helping aspiring business owners navigate persistent structural barriers. Strengthening these mentoring relationships, combined with greater access to digital technologies, could create a more inclusive and supportive entrepreneurial ecosystem.

Professor Kirk Chang, from the Royal School of Business and Law at the University of East London, said the conversation about women’s entrepreneurship needs to evolve alongside changes in the modern workplace. “For years we’ve talked about the barriers women face in business, and those barriers remain real,” he said. “But the world of work has changed dramatically. If we want more women to build successful businesses, we need to rethink the support we give them. Digital skills, flexible ways of working and access to technology should no longer be treated as optional extras. They should be part of the foundation.”

Co-author Dr Ozlem Ozdemir, Senior Lecturer in Business Administration, said traditional models of entrepreneurship no longer reflect the realities of today’s business environment. “Too often we ask how women can succeed within traditional models of entrepreneurship,” she said. “Our research suggests it is time to rethink the model itself. As business becomes increasingly digital, we need new ways of supporting women that reflect how modern businesses actually operate.”

The researchers emphasise that technology alone will not eliminate the challenges women face. They argue that digital tools must be accompanied by investment in digital literacy, inclusive workplace practices and stronger institutional support from governments, educators and business development organisations. By adopting this broader approach, they hope their new framework will help shape more effective policies and programmes that enable more women to launch, grow and sustain successful businesses in an increasingly digital economy.

More information: Kirk Chang et al, Women entrepreneurship theory through digital workplace innovation: a new concept, Journal of Management Development. DOI: 10.1108/JMD-06-2025-0331

Journal information: Journal of Management Development Provided by University of East London

Why Humans Evolved to Be Overconfident

Researchers at the University of Bath and The London School of Economics and Political Science (LSE) believe they have solved a long-standing evolutionary mystery: why humans remain persistently overconfident despite the costly mistakes it can cause. Published in Psychological Review, the study argues that overconfidence—believing you are more capable than you really are—has endured through evolution not in spite of its costs, but because of them. The researchers compare overconfidence to a peacock’s tail, an elaborate but burdensome feature that survives because only the healthiest birds can afford to carry it. Likewise, they suggest that human self-belief acts as a costly signal of underlying ability.

“Overconfidence is strikingly common and often costly,” said Professor Chris Dawson, a behavioural economist at the University of Bath’s School of Management. It contributes to failed businesses, excessive risk-taking and poor decisions, yet evolution has not eliminated it. Instead, the researchers argue that the costs of overconfidence are unevenly distributed. People with greater ability are less likely to suffer severe consequences from inflated self-belief, allowing them to project confidence more successfully than those with lower ability. As a result, overconfidence remains a credible indicator of competence because only the most capable individuals can consistently sustain it.

The researchers also argue that confidence provides important social and professional advantages. “Confidence opens doors,” said Professor Dawson. Confident individuals are more likely to gain influence, attain leadership positions, secure promotions and form valuable relationships. However, confidence alone is not enough to guarantee success. Once opportunities arise, genuine ability determines who performs well. If overconfidence carried no cost, anyone could exaggerate their abilities without consequence, making self-belief meaningless as a signal. Its credibility depends on the fact that excessive confidence is more costly for less capable individuals.

The study builds on a theory proposed by evolutionary biologist Robert Trivers, who suggested that self-deception evolved because genuinely believing our own claims makes us more convincing to others by eliminating subtle signs of dishonesty, such as nervousness or vocal strain. However, the new research addresses a question left unanswered by Trivers: if overconfidence is so common, why do people not simply dismiss confident claims? Professor David de Meza of LSE explains that although people naturally discount others’ self-belief, those who are not overconfident risk being underestimated. Because inflated confidence remains costly, it continues to provide meaningful information about underlying ability.

The findings may also help explain why men generally display higher levels of overconfidence than women. According to Professor Dawson, historical differences in mating strategies meant that women often assessed qualities such as status, commitment and resourcefulness—traits that are difficult to observe directly. Overconfidence evolved as a credible way for men to signal these hidden qualities. The researchers stress that this reflects evolutionary pressures rather than conscious behaviour in modern society, offering a possible explanation for long-observed differences in confidence between the sexes.

The study further argues that loss aversion—the tendency to fear losses more than we value equivalent gains—works alongside overconfidence rather than against it. While people often project confidence, they frequently behave more cautiously in practice, preventing excessive risk-taking without undermining the confident image they present. “People talk confidently but act cautiously,” said Professor de Meza. The researchers conclude that overconfidence and loss aversion form a complementary pair, allowing people to seize opportunities while avoiding catastrophic mistakes. They caution that attempts to eliminate these biases could produce unintended consequences by reducing persuasion, ambition and opportunity-seeking, while encouraging greater risk-taking.

More information: Chris Dawson et al, Talking the Talk, Not Walking the Walk: The Coevolution of Overconfidence and Loss Aversion, Psychological Review. DOI: 10.1037/rev0000644

Journal information: Psychological Review Provided by University of Bath

Global Income Inequality Between North and South Deepens

A new study published in the journal New Political Economy suggests that the income gap between the Global North—the world’s advanced economies—and the Global South—the developing economies—has widened substantially over the past six decades. Conducted by economists Jason Hickel and Dylan Sullivan at the Institute for Environmental Science and Technology at the Universitat Autònoma de Barcelona (ICTA-UAB), Spain, the research estimates that the gap has increased by 170% to 270% since 1960. Analysing annual data from 173 countries representing 99.9% of the global population, the study challenges the widely held belief that poorer nations are steadily catching up with wealthier ones through economic growth and market liberalisation.

The researchers found that while some measures suggest limited relative convergence, the overall picture remains one of widening inequality. Since 1960, the economies of the Global North captured four to ten times more income growth than those of the Global South, depending on the method of comparison. The relative income of the Global South improved by no more than three percentage points, and even this modest gain was driven almost entirely by China’s economic rise. Excluding China, the relative position of developing economies actually deteriorated. Meanwhile, the share of the world’s population living in the Global South increased from 80% in 1960 to 86% in 2023, highlighting the persistence of the global economic divide.

China emerged as the study’s notable exception. Although it has significantly improved its relative economic standing, its GDP per capita still reaches only about 22% to 38% of the average level in the Global North. According to the authors, this places China at roughly the same relative position achieved decades ago by regions such as Latin America, West Asia and North Africa, and Eastern Europe before widespread market liberalisation. The findings suggest that China’s experience is unique rather than evidence of a broader trend of convergence among developing economies.

The study also identifies the 1980s and 1990s—the era of neoliberal reforms, structural adjustment programmes, and market liberalisation promoted by the International Monetary Fund and the World Bank—as a period when inequalities between the Global North and South intensified. Four major developing regions experienced prolonged economic contractions during this period. Latin America’s income fell by 7% and required 13 years to recover, while the Middle East and North Africa saw a 25% decline with a 25-year recovery. Eastern Europe and Central Asia experienced a 36% drop over 17 years, and Sub-Saharan Africa suffered a 23% decline that took 36 years to reverse. By comparison, the Great Recession reduced incomes in advanced economies by only 4%, with recovery occurring within six years.

Although several countries, including South Korea, Taiwan, Greece, Portugal and a number of Eastern European states, have been reclassified by the International Monetary Fund as advanced economies since 1980, the authors argue these cases are exceptional rather than representative. They contend that these countries were incorporated into the economic core largely because of geopolitical considerations, particularly during and after the Cold War. The study notes that the United States provided extensive economic and military assistance to strategic allies, citing South Korea and Israel as examples of countries that received extraordinary levels of support compared with most developing nations.

According to the researchers, the evidence challenges the conventional view that poorer countries are simply following the same development path as wealthier nations with a time lag. Instead, they argue that the divide between the Global North and South reflects structural features of the global economic system rather than a temporary development gap. They conclude that achieving sustained development in the Global South may require strengthening domestic industrial capacity, expanding South–South trade, reducing dependence on advanced economies and major reserve currencies, and addressing the structural barriers that continue to shape global economic inequality.

More information: Jason Hickel et al, The myth of catch-up development: trends in core–periphery inequality from 1960 to 2023, New Political Economy. DOI: 10.1080/13563467.2026.2659076

Journal information: New Political Economy Provided by Universitat Autonoma de Barcelona

Understanding Eras: Discovering Audience Preferences Through Nostalgic Connections

When brands invest millions in nostalgia-driven advertising—such as Super Bowl commercials—they face a critical question: what if they choose the wrong era? Nostalgia is a powerful marketing tool, but its effectiveness depends on whether it resonates with the intended audience. Researchers at the University of Arizona have developed the Nostalgia for Eras Scale. This new measurement tool helps marketers identify which historical periods evoke the strongest nostalgic feelings among different groups. Their findings, published in the Journal of Advertising, provide a more precise way to understand audience preferences and improve marketing strategies.

Developed by Caleb Warren, professor and Robert A. Eckert Endowed Chair in Marketing at the Eller College of Management, and Matthew Farmer, now an assistant professor at Utah Valley University, the scale addresses an important gap in existing research. Previous studies typically measured nostalgia for personal memories or the past in general. In contrast, Warren and Farmer argue that people are often nostalgic for broader periods of time—whether personal life stages, such as university years, or collective eras, such as the 1950s or 1980s. Understanding these preferences enables marketers to create campaigns that connect more deeply with consumers.

To develop the scale, the researchers analysed consumer essays, previous academic studies, news coverage, and more than 200 advertisements. Their work identified three core elements of nostalgia: the warmth associated with remembering the past, a sense of loss because that time has passed, and the belief that life was simpler and more carefree during that period. Using these insights, they designed a measurement tool that identifies which decade or historical era people feel most nostalgic about.

When hundreds of participants completed the assessment, fewer than half identified their late teens or early twenties as the period they missed most. Instead, many selected different stages of life or even historical periods they had never personally experienced. People who had meaningful experiences later in adulthood, for example, often felt stronger nostalgia for those years. Others idealised eras such as the 1950s, the 1980s, or even the Old West, demonstrating that nostalgia is shaped by personal experiences, cultural influences, values, and identity—not simply by age.

The researchers then tested whether these preferences influenced consumer behaviour. Participants who expressed strong nostalgia for the 1990s responded more positively to a 1990s-era eBay advertisement than to a contemporary version. Participants whose nostalgic preferences centred on other decades did not show the same response. The scale also successfully predicted which film trailers participants were more likely to watch based on the historical periods they found most nostalgic, highlighting its value for advertising, entertainment, and market research.

Rather than relying on intuition or assumptions about generational preferences, marketers can use the Nostalgia for Eras Scale to identify the historical periods that resonate most with specific audiences. Whether promoting a brand, producing a film, or creating a period drama, understanding nostalgic connections allows organisations to tailor content that is more emotionally meaningful and engaging. By replacing guesswork with evidence-based insights, the scale offers a practical framework for predicting audience preferences and creating more effective, emotionally resonant marketing campaigns.

More information: Matthew Farmer et al, Conceptualizing and Measuring Nostalgia for Eras, Journal of Advertising. DOI: 10.1080/00913367.2026.2686662

Journal information: Journal of Advertising Provided by University of Arizona

Clear Communication About Price Increases Builds Customer Trust

Simply explaining where customers’ money goes could make them more willing to accept higher prices, according to new research from the University of Surrey. Published in the Journal of Service Research, the study found that businesses can increase customers’ willingness to pay by explaining how their money supports the aspects of a service that customers value most, such as skilled staff, talented artists or high-quality ingredients, rather than focusing on overhead expenses like administration or advertising.

The findings challenge the common assumption that consumers care only about the final price. Instead, the researchers found that when customers understand what their money is funding, they are more likely to perceive prices as fair and voluntarily pay more. Greater transparency about the value behind a product or service can therefore strengthen customer trust while reducing resistance to price increases.

To investigate this relationship, the research team examined six service sectors: restaurants, museums, dance workshops, guided tours, online courses and newspaper subscriptions. The study combined two field experiments with six experimental studies involving a total of 2,606 participants. Participants were presented with a variety of real and hypothetical pricing scenarios and asked to decide how much they would be willing to pay after receiving different explanations about how business costs were allocated.

Across nearly every setting, participants who received information about customer-facing costs consistently paid more than those given no explanation or information focused on behind-the-scenes operating expenses. The effect was particularly strong among individuals who would otherwise have chosen to pay the least, suggesting that transparency can be especially effective in increasing price acceptance among more price-sensitive customers.

Lead author Dr Brigitte Stangl, Associate Professor at the University of Surrey, said the findings demonstrate that customers are not simply looking for the lowest possible price. Instead, they are often willing to pay more when they understand the value they receive and how their payments directly support the quality of the service. She emphasised that businesses do not need to disclose confidential financial information; rather, highlighting customer-facing investments such as expert staff, talented artists or premium ingredients is sufficient to improve perceptions of fairness.

Overall, the study found that explanations centred on costs customers can directly appreciate consistently outperformed messages focused on general operating expenses, such as administration, marketing or building costs. By clearly communicating how customer payments contribute to service quality, businesses can build greater trust, increase perceptions of fairness and encourage customers to accept higher prices more willingly—an approach that may prove particularly valuable as organisations continue to navigate rising operating costs and the challenge of communicating necessary price increases.

More information: Brigitte Stangl et al, The Impact of Cost Structure Appeals on Fairness Perceptions and Payments, Journal of Service Research. DOI: 10.1177/10946705251341080

Journal information: Journal of Service Research Provided by University of Surrey

Public Research as the Foundation for Private Investment and Growth

Strategic public investment in research and development (R&D) can strengthen the economy almost immediately while encouraging private sector investment for years to come, according to a new study led by the University of Southampton. Conducted in collaboration with UCL and the World Bank and published in The Economic Journal, the research finds that government-funded R&D is a particularly productive form of public investment. Rather than displacing private innovation, it stimulates additional business investment and economic activity even before the full technological benefits of research are realised.

Lead researcher Dr Vincenzo De Lipsis says the findings have important implications for governments seeking to stimulate growth while managing constrained public finances. “At a time when governments are seeking to rebuild industrial capacity while operating within tight fiscal constraints, our findings show that the composition, design and credibility of public investment can be as important as its overall size,” he says. The team set out to understand how quickly public R&D generates wider economic benefits, how large those benefits become, and whether they endure over time.

To answer these questions, the researchers analysed more than 280 quarterly economic observations from the US Bureau of Economic Analysis spanning 1947 to 2017. The dataset included public and private investment, government expenditure, tax revenues and gross domestic product (GDP). The United States’ long history of public investment in innovation enabled the team to examine how government-funded R&D influences the economy over several decades and to trace both its short- and long-term effects.

The analysis showed that public R&D delivers substantially stronger and longer-lasting economic benefits than conventional government spending. A key reason is its ability to “crowd in” private investment by encouraging businesses to increase their own research spending. The researchers estimate that every additional dollar invested in public R&D generates between $2.60 and $4.30 in additional economic output within a year, highlighting its effectiveness as an engine of economic growth.

The study also suggests that the impact of public R&D begins before projects are fully underway. When governments make clear, credible long-term commitments to research and innovation, businesses may adjust their investment plans in anticipation, reducing uncertainty and increasing confidence. According to the authors, governments are uniquely positioned to stimulate innovation because they can support high-risk, long-term research and use innovation-oriented procurement to help create new markets and strengthen productive capacity.

The researchers conclude that public and private R&D should be viewed as complementary rather than competing forms of investment. Public funding is well suited to tackling long-term, high-risk challenges and laying the scientific and technological foundations for innovation, while private firms are better placed to transform those discoveries into commercially viable products and services. Together, sustained public investment and private sector innovation can deliver stronger economic growth, greater resilience and lasting benefits for society.

More information: Vincenzo De Lipsis et al, Macroeconomic Effects of Public R&D, The Economic Journal. DOI: 10.1093/ej/ueag061

Journal information: The Economic Journal Provided by University of Southampton